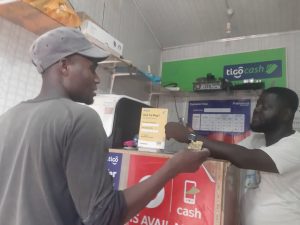
It is 6:30am and as usual Felix Obeng Amoako is on time as he reports to work at his mini blue container shop where he operates his Mobile Money (MoMo) business.
Felix has been operating Wistec Obeng Enterprises for over six years but the MoMo business has been his main occupation for about three years after he registered to be a merchant for MTN Mobile Money three years ago after his internet café business took a nose dive due to the advent of affordable smartphones which paved way for internet penetration.
Located at Lapaz, just behind the Papaye restaurant, Felix serves hundreds of customers in a day providing primary services including MoMo deposits and withdrawals. He also provides secretarial services.
In a day, Felix who is in his late 30s, is able to record an average of GHc100 as revenue, out of which he uses some to take care of his wife and pay for school fees of his two children.
He explained that coming early helps him to serve customers who leave home early wanting do MoMo transactions before heading to work.
Some even withdraw in order to pay for their transportation to work,” he noted.
Felix plans to expand his MoMo operations to other areas to cater for many more people.
MoMo has brightened the future for me and it can only get better,” remarked Amoako.
Another such beneficiary of the MoMo business is Kwame Odoru who operates around the Lapaz main traffic light.
The MoMo business is my life. The commissions and interest are what I’m using to cater for my family, I don’t have anything else doing,” said Odoru.
According to GSMA’s 2019 Global Adoption Survey, $1.1 billion in commissions were paid directly to 1.4 million agents, which is equivalent to an average of $841 in additional annual income. “Although some agents shifted their core business activity from airtime sales to mobile money, and some were small shopkeepers who became mobile money agents, the analysis showed that the additional monthly income agents are earning from commissions is enough to put a child through primary and secondary school in some countries, including Côte d’Ivoire and Ghana,” the survey stated.
In markets where one agent can offer services for multiple mobile money providers, a successful agent could earn several times that amount. Also, since most agents operate a micro-retail business in addition to their mobile money business, adding a stable and reliable income means they are better able to spread costs across multiple businesses.
According to statistics, there are about 200,000 MoMo operators within Ghana providing lifesaving services to millions of Ghanaians but only about 15,000 is registered with the Mobile Money Agents Association Ghana. Also, the latest Economic and Financial Data from Bank of Ghana revealed that the total value of MoMo transactions has grown to GH¢569 billion in 2020 from GH¢32.8 billion in 2019. The increase was largely attributed to the Covid-19 pandemic which restrictions propelled more Ghanaians to send cash to their relatives and friends through MoMo.
The data further indicated that there are 38.5 million registered MoMo accounts in Ghana as at the end of December 2020 as against 32.5 million in December 2019.
MoMo is far more accessible than any other type of digital financial service (including app-based platforms), particularly outside of urban centres. As a result, in many markets, MoMo has become integral to the national Covid-19 response and provided a critical path to delivering financial assistance quickly, safely and efficiently as noted in the GSMA’s 2019 State of the Industry Report on Mobile Money. In Ghana, MTN took a bold step to reduced MoMo charges by waiving fees on transactions of GHS100 and below and increased wallet limits to promote the use of MoMo during the pandemic. Other network operators like Vodafone latter followed suit.
MoMo today represents a fundamentally transformational opportunity to connect billions of people to the formal and informal economy, the unbanked and banked citizens of the world.
At the recent Mobile Money Africa Conference in Johannesburg, delegates agreed that MoMo is transforming African economies by improving peoples’ lives and creating choices of financial services for the previously unbanked. It is, therefore, not surprising that Mobile Money, the ground-breaking low-cost banking solution introduced by MTN has shown a double-digit, month-on-month growth.
There are plenty of lessons across the continent on mobile money services, and its impact on the lives of ordinary people, as well as its ability to bring convenience to the rest of the populace.
In Ghana, for instance, MTN is offering life insurance to MoMo customers. It has also given users the ability to save and borrow money through their cell-phones while also earning interest.
However, to ensure MoMo services continue to grow, more innovative solutions are required, and to achieve that, partnerships are critical.
For instance, in 2019, MTN Group opened its MoMo API programme in seven countries (Benin, Cameroon Congo, Côte d’Ivoire, Ghana, Uganda and Zambia) to foster innovation and enhance financial inclusion.
In addition to innovation and partnerships, there a number of challenges which need to be addressed to accelerate the growth of MoMo into the future.
These include operational challenges, such as driving usage and attracting customers; regulatory issues; a lack of financial education and examples of best practice; underinvestment; and infrastructure and network challenges. But all of these can be overcome through partnerships with suppliers and regulators alike.
The empowerment that comes with owning a MoMo account cannot be over emphasized. More women are using financial services, low-income households are accessing essential utility services and smallholder farmers are getting paid more quickly and conveniently. Meanwhile, millions of migrants and their families are experiencing the life-changing benefits of faster, safer and cheaper international remittances and humanitarian cash assistance is being delivered more thoughtfully to those in crisis situations. All of this is unlocking new solutions to some of the world’s most intractable development challenges and highlighting the catalytic role that mobile money is playing in achieving the Sustainable Development Goals.
Source: Kofi Ahovi
Comments